Crypto loans let you access liquidity without selling your crypto. You can use Bitcoin, Ethereum, stablecoins, or other supported assets as collateral and borrow funds against them.
But the best crypto loan platform is not necessarily the one with the lowest advertised rate. The important questions are how much collateral you need, what happens if its value falls, who controls the assets, and how easily you can repay the loan.
The three things that matter most
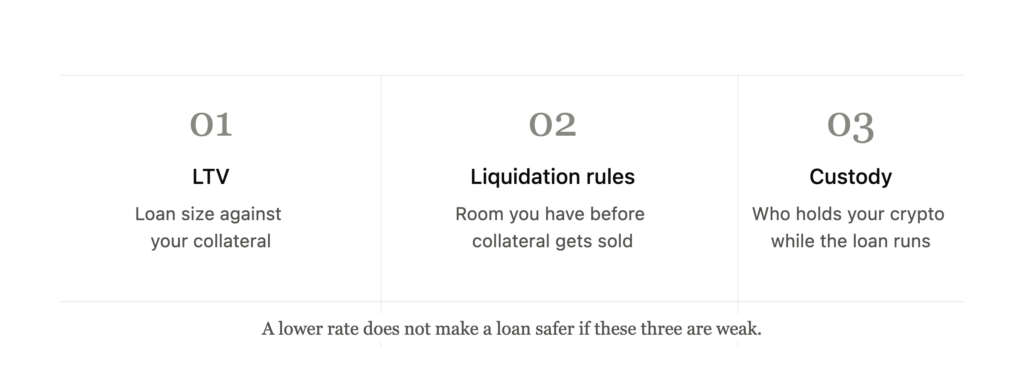
A crypto loan can look attractive until you check the details behind it.
- LTV tells you how large the loan is compared with your collateral.
- Liquidation rules tell you how much room you have before the collateral can be sold.
- Custody tells you who controls your crypto while the loan is active.
A lower interest rate does not automatically make a loan safer if the liquidation terms are aggressive or the collateral is held under a structure you are not comfortable with.
CeFi vs DeFi: the real difference
| CeFi | DeFi | |
|---|---|---|
| Account | Usually email/app based | Usually wallet-based |
| Custody | Platform or its custody partners | Smart contracts |
| Interest | Usually set by the lender/product | Often market-driven |
| Liquidation | Platform-specific rules | Smart-contract rules |
| Main risk | Counterparty and custody | Smart contracts, oracles, and liquidation |
| Best for | Simpler borrowing | On-chain users |
Neither model is necessarily safer than the other.
With CeFi, you need to know the organization, custodian, and the loan terms. In DeFi, you need to know the smart contract, the collateral requirements, and the liquidation process.
Top 10 crypto loan platforms
1. Aave
Aave is one of the most established DeFi lending protocols. Instead of applying for a traditional loan, users supply crypto to the protocol and can borrow supported assets against their collateral.
Borrowing rates can change with market conditions, and borrowers have to monitor their health factor. On Aave, a health factor below 1 means the position is at risk of liquidation.
Pros:
- Non-custodial DeFi model
- Wide variety of assets and markets
- Positions recorded on the blockchain
- Repayment flexibility
Cons:
- Liquidity risk can shift fast in times of volatility
- Variable borrowing costs
- Requires a basic understanding of wallets and DeFi
Best for: Experienced crypto users who want on-chain borrowing.
2. Morpho
Morpho takes a different approach to DeFi lending. Its Morpho Blue system uses isolated markets, where each market has its own collateral, loan asset, oracle, and risk factors.
This makes the risk structure easier to separate between markets. Still, it also means borrowers have to choose the market carefully rather than treating Morpho as a single universal lending pool.
Morpho also uses LLTV, or Liquidation Loan-to-Value, to define when a position becomes eligible for liquidation.
Pros:
- Isolated market-based structure
- Clear risk factors
- Excellent on-chain flexibility
- Ideal for more experienced borrowers
Cons:
- More complicated than the average CeFi platform
- Market selection matters
- Borrowing conditions vary between markets
Best for: DeFi users who want more control over market and risk settings.
3. Nexo

Nexo provides an old-fashioned borrowing service but keeps crypto as its backing. You can borrow against assets Nexo accepts without selling them, and borrowing limits depend on asset type, LTV, and account status.
The system itself resembles crypto credit lending rather than just a single fixed loan. This makes it suitable for people who may need to repay and reuse funds later.
Pros:
- Simple user experience
- Large range of supported assets
- Flexible credit-style borrowing
- No need to have credit history for crypto lending
Cons:
- Terms vary according to eligibility and account requirements
- Centralized custody system
- Availability varies by jurisdiction
Best for: Users who want a familiar app-based borrowing experience.
4. Binance Loans
Binance Loans brings borrowing capability right into the Binance platform. The Binance Loans platform offers various loan instruments, including flexible and fixed-rate loans, which is an added advantage for users who hold their money on Binance.
The main advantage is convenience: you don’t need to move between multiple platforms to use collateral and receive the loan.
Pros:
- Convenient for Binance users
- Multiple loan structures
- Wide crypto ecosystem
- Easy access through the exchange interface
Cons:
- Centralized system
- Different conditions for different kinds of loan products
- Accessibility depends on the region and assets
Best for: Binance users who want to borrow without leaving the exchange ecosystem.
5. Ledn

Ledn focuses heavily on Bitcoin-backed lending rather than trying to become a general-purpose DeFi protocol.
Its Dollar Loan product uses Bitcoin as collateral and follows a more traditional lending structure, making it easier for borrowers to understand if they want a dedicated BTC-backed product. Ledn currently publishes its loan terms and custody information publicly.
Pros:
- Well oriented towards Bitcoin
- Structured loan process
- Designed around long-term BTC holders
- More familiar lending experience than DeFi
Cons:
- Less suitable for users holding many different assets
- Centralized lending model
- Loan availability depends upon jurisdiction and eligibility
Best for: Bitcoin holders who want to borrow without selling their BTC.
6. YouHodler
YouHodler combines a crypto lending platform with a fintech interface. The platform offers various crypto assets users can borrow against.
The platform mainly focuses on crypto lending and doesn’t require users to understand DeFi technology.
Pros:
- Easy-to-use interface
- Supports many crypto assets
- Multiple borrowing options
- Designed for retail users
Cons:
- Centralized custody
- Conditions for lending differ according to type of asset
- Increased LTV could also mean lower safety versus market drops
Best for: Retail investors looking for a crypto loan instead of a DeFi one.
7. CoinRabbit
CoinRabbit highlights efficiency and simplicity. Instead of creating a complicated DeFi position, users can use their crypto assets to generate liquidity.
The platform is especially attractive to those who prefer simplicity over complicated lending processes.
Pros:
- Easy lending process
- Quicker access to funds
- Works with various cryptocurrencies
- No bank loan application process
Cons:
- It is a centralized system
- The interest rate on loans is dependent on the asset
- Risk of collateral liquidation exists
Best for: Borrowers who favor speed and a simple process.
8. Compound

Compound is another major DeFi lending protocol. Users supply supported assets and can borrow against them, with each market setting borrowing conditions.
Unlike a traditional lender, Compound doesn’t rely on a personal loan application. The protocol’s smart contracts manage the lending process and collateral requirements.
Pros:
- Already established DeFi structure
- On-chain clear transactions
- No credit application process needed
- Various kinds of cryptocurrency collateral
Cons:
- Terms may vary
- Possibility of smart contract and oracle issues
- Needs a compatible crypto wallet
Best for: DeFi users looking for an established alternative to Aave.
9. Maple

Maple differs from most platforms on this list because its lending products increasingly focus on professional and institutional borrowers.
Its 2026 Borrower Hub is designed specifically for institutions rather than everyday retail users. That makes Maple more relevant for businesses, trading firms, digital asset companies, and other professional borrowers.
Pros:
- Based on an institutional model
- Designed for those who need to borrow more
- Structured professional borrowing process
- Perfect for cryptocurrency companies
Cons:
- Not designed for ordinary consumers
- Difficult onboarding procedure
- Borrowing depends on institutional eligibility
Best for: Companies and professional crypto market participants.
10. Unchained

Unchained focuses specifically on Bitcoin-backed lending and uses a collaborative custody structure for its lending products.
This model differs from simply sending BTC to a centralized service. Unchained’s approach uses multisignature custody, giving the borrower a greater role in controlling the collateral.
Pros:
- Bitcoin-focused
- Multisignature custody structure
- Designed for larger borrowers
- Very transparent about collateral
Cons:
- Not aimed at small retail loans
- BTC-focused rather than multi-asset
- Eligibility and loan requirements are more restrictive
Best for: Businesses and serious Bitcoin holders looking for a BTC-backed loan structure.
Crypto loan platforms compared
Crypto loan platforms can look similar on the surface, but they work very differently. Some use smart contracts and let borrowers manage everything on-chain, while others provide a more traditional lending experience through a centralized company.
| Platform | Model | Main collateral | Loan type | Rate model | Best for |
|---|---|---|---|---|---|
| Aave | DeFi | Multiple crypto assets | Crypto/stablecoins | Variable | DeFi borrowing |
| Morpho | DeFi | Market-specific assets | Crypto/stablecoins | Variable | Advanced DeFi users |
| Nexo | CeFi | BTC, ETH and other assets | Fiat/stablecoins | Variable/tier-based | Flexible crypto credit |
| Binance Loans | CeFi | Supported crypto assets | Crypto/stablecoins | Product-dependent | Binance users |
| Ledn | CeFi | Mainly BTC | Stablecoins/fiat-linked | Fixed products available | Bitcoin holders |
| YouHodler | CeFi | Multiple crypto assets | Fiat/stablecoins | Product-dependent | Retail borrowers |
| CoinRabbit | CeFi | Multiple crypto assets | Stablecoins/crypto | Product-dependent | Fast borrowing |
| Compound | DeFi | Supported crypto assets | Crypto/stablecoins | Variable | DeFi users |
| Maple | Institutional DeFi | Digital assets | Institutional financing | Deal-dependent | Businesses & institutions |
| Unchained | Bitcoin lending | BTC | Fiat-backed loan | Product-dependent | Bitcoin businesses |
Key risks of crypto loans
A crypto loan can give you liquidity without selling your assets, but it also creates risks that are easy to overlook.
- Liquidation risk – if the collateral falls too far, the platform may sell part of it to repay the loan.
- Market risk – sudden changes in crypto market value can affect your LTV ratio.
- Interest rate risk – floating interest rates can increase borrowing costs.
- Platform risk – centralized lenders can create counterparty and custody risks.
- Smart contract risk – DeFi loans depend on code, oracles, and protocol parameters.
- Liquidity risk – in stressed market conditions, closing or refinancing a position may become harder.
- Asset risk – using a highly volatile token as collateral can leave less room before liquidation.
Main takeaway: the real cost of a crypto loan isn’t just the interest rate. It also depends on how much collateral you put at risk and how the platform handles liquidation.
How a сrypto-backed loan actually works
Deposit collateral
↓
Choose loan asset
↓
Borrow
↓
Monitor LTV/health
↓
Repay
↓
Unlock collateral
Unlike a traditional loan, a crypto-backed loan is continuously linked to the value of your collateral. If that value falls enough, the position can become eligible for liquidation. Aave and Morpho both require borrowers to monitor their position’s health.
The five questions to ask before depositing collateral
1. Who will control my collateral?
2. What will happen in case of sudden depreciation in its value?
3. Will I be paying a fixed or floating interest rate?
4. Do I have the freedom to make payments at any time?
5. What will I get in return: fiat currency, stablecoins, or cryptocurrency?
If you cannot answer all five, you may not know the loan well enough to take it.
Which crypto loan platform should you choose?
No single platform is best for every borrower.
| If you want… | Consider |
|---|---|
| DeFi borrowing | Aave |
| Isolated DeFi markets | Morpho |
| Flexible crypto credit | Nexo |
| Borrowing inside an exchange | Binance Loans |
| Bitcoin-backed borrowing | Ledn |
| Retail-friendly borrowing | YouHodler |
| Fast access to liquidity | CoinRabbit |
| Another established DeFi option | Compound |
| Institutional borrowing | Maple |
| Bitcoin business lending | Unchained |
FAQ
How does a crypto loan work?
A crypto loan allows you to borrow money or stablecoins using your crypto as collateral. Instead of selling your BTC, ETH, or another supported asset, you lock it with the lender or protocol and receive a loan against its value. The amount you can borrow depends on the asset, its LTV limit, and the platform’s lending terms.
What happens if my collateral loses value?
If your collateral’s price decreases, the loan becomes riskier. This is because the LTV ratio increases: you still owe the same loan amount, but with less collateral. When the position becomes liquidated, some of your collateral may be sold to repay your loan.
Is it better to borrow against crypto or sell it?
A crypto-backed loan makes sense when you need to keep your crypto while accessing its liquidity. However, it comes with interest rates and liquidation risk. If you sell your crypto, the interest and debt will disappear, but your position will also close, which means you won’t get any profit if the asset’s price increases.
What should I check before choosing a crypto loan platform?
Consider the overall loan structure, not just the quoted interest rate. Consider the LTV ratio, liquidation rules, interest rate, repayment terms, and how the platform stores the collateral. You may also want to check whether early repayment is possible and which assets it supports.
Conclusion
The choice of the best crypto lending platform is not so much about the interest rates but rather how the loan suits your circumstances. Aave, Morpho, and Compound suit those comfortable handling on-chain transactions, while Nexo, Binance, and YouHodler are simpler.
Ledn and Unchained are examples of platforms more specialized in lending BTC. Maple occupies a different niche because it focuses on lending to businesses and institutions.
Before taking a loan, look beyond the amount you can borrow. Check the LTV, liquidation rules, interest structure, custody model, and repayment conditions. A loan that looks attractive at the start can become expensive or difficult to manage if the value of your collateral falls.
The main goal should be simple: borrow only what you can comfortably manage if the crypto market moves against you.